
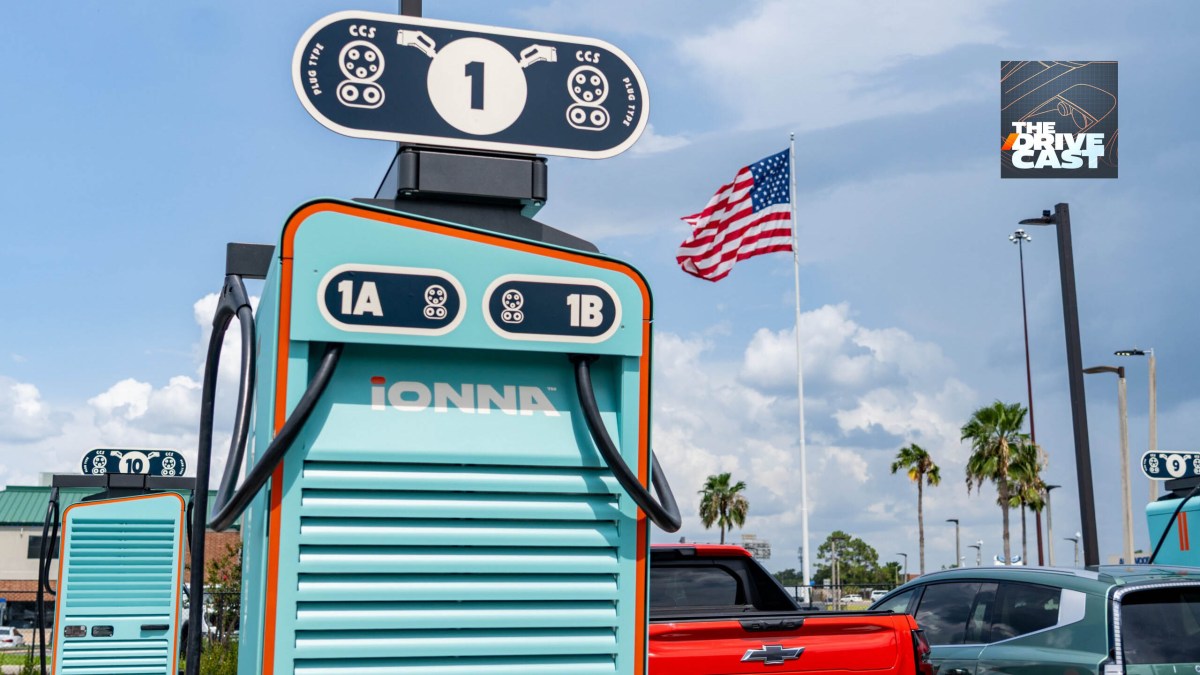
formed a partnership labeled Ionna to establish a national network of rapid chargers in competition with Tesla’s Superchargers. Subsequently, Toyota came on board a year later, increasing the count to eight. In the latest chapter of The Drivecast, Ionna’s CEO Seth Cutler engaged in an exclusive conversation with The Drive, addressing the delays, current status, and whether EV fast-charging infrastructure will truly evolve to meet the needs for a successful transition in America.
Despite a slowdown in electric vehicle adoption in the US, it remains on track. Currently, approximately 5.7 million EVs are active on American roads, with new registrations occurring daily. However, the US has only around 250,000 public chargers for those drivers, and out of those, merely 73,000 are the desired DC fast chargers, capable of recharging an EV in under 30 minutes. For anyone who’s recently tried using an Electrify America station, the experience often feels frustrating due to frequent malfunctions. The only organization currently excelling in this space is Tesla, which, although has made their charging standard accessible to other car manufacturers, still doesn’t suffice.
The objective of Ionna is straightforward: to construct a dependable, high-powered fast-charging network for electric vehicles across North America, aiming for at least 30,000 chargers and 2,000 stations in the U.S. by 2030, followed by Canada. Seth Cutler has been designated as Ionna’s CEO and tasked with bringing this vision to fruition.
New to this conversation? The Drivecast is The Drive‘s weekly podcast offering an insider’s view of the major controversies, narratives, and figures shaping the automotive landscape and the current state of our roads. Backed by The Drive‘s exclusive access, original journalism, and insights, The Drivecast aims to turn everyone into an insider.
Catch The Drivecast on Spotify, Apple Podcasts, or Amazon Music. Enjoy it? Support it? A five-star review on your preferred platform would aid in reaching a broader audience. Suggestions, tips, requests, or feedback? Reach out at [email protected]. We assure you, every email is read.
Full Transcript
Kyle: A significant day on The Drivecast. We have Joel back from fishing—he survived and hopefully caught plenty. Seth Cutler, CEO of Ionna Charging, joins us to discuss why the charging situation in America is as it is and the steps being taken towards improvement. Seth, welcome.
Seth: Thank you. Great to be here.
Joel: Happy to have you, Seth. And yes, I caught a lot of fish—everything from crappies and northerns to some perch and stunning walleye. I landed a beautiful 24-inch walleye; it was impressive. But let’s not dwell on my fishing trip. Seth, we’ve met before. You unexpectedly joined one of my interviews with your board member. It was quite enjoyable. Let’s start with the tough question: why is America’s EV charging scenario such a complete disaster? What’s the reason?
Seth: Essentially, it boils down to a couple of factors. One is that in a fledgling industry or market like this, new equipment consistently comes to market, there’s a shortage of trained personnel to service that equipment properly, and various technology interoperability issues need to be resolved. Truthfully, having a first-mover advantage isn’t always beneficial in a market. Sometimes being a second or third entrant can actually be advantageous—better to be fortunate than merely skilled, and this has played to Ionna’s benefit. The second key piece is ensuring that we are building and concentrating on the right elements. It’s easy to lose sight of, “We’re just trying to establish chargers to create a national network,” versus “We’re aiming to develop charging stations that serve drivers and provide an exceptional experience.” While that distinction might not seem significant, it undeniably influences cultural behaviors within an organization, yielding markedly different outcomes for customers.
Kyle: Just to elaborate on that, every industry has its unique challenges and characteristics, EV charging being a relatively new one—though not entirely new, considering the first public chargers appeared on American roads back in 2007, marking nearly 20 years. One could argue that the initial years of gas stations were also fraught with problems and copious learning experiences. From a general consumer perspective, non-EV drivers might perceive gas stations as more complex, given the construction involved, underground tanks, environmental considerations, and the significant convenience store presence—all of which aren’t as visible with EV charging stations, which seem just like some cables. I understand it’s more complex than that, but many people fail to grasp why progress remains slow. Why is growth at its current pace? Why hasn’t it achieved the anticipated heights from five years ago?
Seth: That’s a valid question. Often, people relate it to gas stations, but I liken it more to cellular communication or cell towers. I recall my parents acquiring their first cell phone in the early ’90s; it wasn’t until 2026 that people genuinely felt comfortable replacing their landline with a cell phone as their primary communication device, finding it reliable and adequately covered. That transition took over 20 years. I perceive a parallel to our situation: a nascent market with a limited number of cars; consequently, I won’t establish 1,000 chargers in California simultaneously with just 10 cars on the road; I’ll only deploy what’s feasible for capital allocation. Comparing it in that light brings interesting insights.
Regarding the complexity of constructing these charging stations, several overlooked factors contribute. First, deploying energy or power density in a space typically reserved for mall development comes with its own challenges. Think about constructing a mall; that process can take three to five years. I need to first plan, navigate planning boards and zoning approvals, and then actually build. Completing mall construction could take over a year. When we finalize a site for charging—not solely us but any entity—you could have shovels in the ground following permits within a week, and utility power active within six weeks. We’ve even managed sites in four weeks. Utilities aren’t equipped for that speedy pace; they aren’t accustomed to such quick mobilization. The entire charging initiative—from site acquisition and leasing parking spaces to utility engagement and rapidly delivering power to small areas—is intricate, particularly as many of these stations remain unmanned. How can we ensure that even without personnel on-site to oversee and maintain the chargers, we develop a model that incorporates telemetry and data to remotely diagnose, monitor, and resolve issues? Or ensure staff is within two hours of every site to continually address any operational failures? It’s honestly more than just laying cables and erecting posts. An entire industry has emerged over the last two decades focused on charging.
Kyle: That offers an excellent perspective. We’ll revisit the maintenance aspect later, as that clearly resonates: chargers that often can’t be utilized—this isn’t about Ionna specifically, but the broader negative reputation the sector has developed. Now, let’s delve into Ionna’s growth specifically. The initial aim when the company was established as a collaboration amongst seven automakers—following Toyota’s join was to set forth on 30,000 chargers and 2,000 stations by 2030. Where do you currently stand?
Seth: We’re currently operating roughly 185 stations available to the public. It’s essential to provide context on the company’s history and current state. We commenced operations as a company in February 2024, so we’ve been functioning for just two and a half years, establishing a team, and so on. Our initial site was opened a year and a half ago, transitioning from zero sites to around 180. We have another 100 sites under construction, alongside several hundred more that are progressing through permits, power, and poised to start building. Presently, we have about 600 sites under contract, with an expectation of exceeding another 100 contracts by year’s end. We’re making significant progress in a relatively short duration. There’s a considerable challenge ahead, undoubtedly, but numerous individuals in this industry have propagated grand promises and visions. Our distinct focus revolves around an unwavering commitment to delivering a superior driver experience. That’s our objective. We’re not diving into battery storage at this moment. We’re not developing a mobile app. We’re not attempting to amplify profits through driver lounges or snack sales. Our singular focus lies in enhancing charging quality at scale, which explains our rapid advancements over a brief period.
Kyle: I’m jumping ahead a bit here, but you just made a statement I wish to explore. You touched on potato chips. Within gas stations, the primary income stems not from gas sales but from the convenience store offerings. The profit margins on gasoline, especially for a single station owner or small franchisee, are quite slim. As Ionna develops the Rechargery concept and endeavors to provide more amenities and services at fast chargers, do you envision this as part of the profit equation—offering various products that customers will purchase, despite the utility and electricity costs not leaving substantial margins?
Seth: I’ll respond by stating: we recognize the company must achieve financial independence and profitability over time. This is a for-profit venture. Infrastructure needs to be profitable; otherwise, it won’t endure, and if it fails, EVs will struggle to thrive. Early on, we identified opportunities to lay the groundwork for future growth. We’ve acquired land at numerous sites; we’ve constructed our own amenities featuring buildings with vending machines, restrooms, and advanced technologies like Amazon Just Walk Out. We’ve taken parcels of land as ground leases, allowing for future developments such as adding buildings or co-tenants. These elements are present as foundational investments, although our current focus has been on ensuring driver quality and charging quality at scale. But we acknowledge that in 2027, 2028, and beyond, we’ll begin allocating resources to explore additional monetization strategies that enhance driver value through these unique offerings. Nonetheless, this is not a current priority.
Joel: Before we transition, I want to revisit your mention of the 185 chargers. Recently, I had the opportunity to interview Rivian’s founder and CEO RJ Scaringe on The Drivecast, who pointed out that—this has been a consistent sentiment from him—there are two reliable and notable EV charging networks in America: Tesla’s Supercharger network, which he has praised extensively, and the Rivian Adventure Network, which as of June comprised 4% of Tesla’s size, with Rivian having approximately 150 stations, just slightly below the 185 you’ve mentioned. He aims to expand into one of the largest networks in the US in the years ahead, emphasizing the critical aspect of high operational uptime. I’m interested in your thoughts on Scaringe’s remarks, especially since your network is slightly larger than theirs at this moment, and I believe you embrace the philosophy of “we’re dependable, we don’t have an app.”
Seth: I hold great respect for RJ and the remarkable achievements of the Rivian team; it truly is impressive, as is Tesla’s accomplishment. Regarding Ionna, J.D. Power ranked us number one in their 2026 survey, which stems from driver feedback collected during their evaluations. This recognition from J.D. Power affirms not just our perceived efficacy, but also that drivers endorse our service. We’re noticing increased utilization and a wave of organic discussions on social media about Ionna and the user experiences, which is quite encouraging. However, a considerable amount of work remains. I’m confident we can improve further and expand our site count significantly. Keep in mind, we’ve only been operational for 18 months since our first location opened. Back in June, our network had around 130 or 140 sites open; we had 80 stations active in January. Over the last nine months, we’ve over doubled our network, and we anticipate surpassing 200 sites by year’s end. My aim is to triple our network size this year from the starting 80 we had at the beginning. The potential growth isn’t fully appreciated as we are advancing at an unprecedented rate.
Kyle: Regarding scale, it appears if this trajectory continues, you are on track for the 2,000 charging station target by 2030. However, achieving 2,000 charging stations that result in 30,000 chargers seems a bit ambitious, given that a considerable number of these stations typically house between four to six chargers. How do you plan to achieve this saturation of 30,000 chargers? While the number of stations is a positive indicator, the actual plugs fundamentally matter for the users.
Seth: There’s ongoing debate about whether it’s about bays, or plugs, or sites. What’s crucial, especially in the current market, is ensuring we have adequate coverage for drivers nationwide so they can travel across states, and effectively within specific urban areas. We’re diligently working to guarantee that when we deploy in a given region, Ionna becomes the go-to network for drivers. In Florida, for instance, we have around 24 or 25 sites operational now. When considering high-powered charging rates at 150 kilowatts and above, we rank as the third largest network provider in all of Florida, just behind Electrify America, based on the number of high-powered bays. That signifies meaningful market coverage. By year’s end, we’re projecting to have about 30 sites active plus several hundred additional bays, thus enhancing our competitive stance in that state. We’re pursuing a similar strategy in Dallas, Houston, and throughout California. Our emphasis right now is on ensuring densely populated regions have sufficient Ionna network coverage they can depend on.
Kyle: On a related note, I have a small grievance with you, Seth. Residing in Los Angeles, we currently have zero Ionna chargers. I know a few are under construction, but they are not directly in LA, more in the broader Southern California region. Contrarily, Joel, living outside Minneapolis, has access to eight Rechargeries currently operational, with a few more on the horizon. LA boasts four times the population of Minneapolis, yet no Ionna presence as of now. I keep checking due to the pictures of these stunning stations you share, but so far, no luck. Why doesn’t LA have a presence while Minneapolis appears to have considerable saturation? Is your expansion strategy based on perceived demand and opportunities, or chiefly on ease of construction?
Joel: We will accept the assertion that Minneapolis is just the superior locale. That’s an acceptable explanation on this podcast.
Seth: Fair point. Initially, my priority was to secure tangible results in the market in terms of active chargers. Thus, in 2024, we needed to recruit staff, pinpoint a headquarters, and actualize this vision. The reality is that we deployed resources in locations conducive to quick deployment, allowing us to gain insights from the ground. Launching a site in LA would take longer and is where utilization is highest. Hence, we aimed to glean knowledge initially in places like Kansas, Raleigh, and Minneapolis. That was my strategy; I sought to ensure that within the initial nine months as a functioning company, we had launched active sites, which was quite an achievement. At present, we have over 100 sites contracted across California. In California, we have more than 30 sites already constructed or operational, so we are focused on accumulating scale in the state. In Northern California, within PG&E territory, we expect more than a dozen sites to be operational before year’s end. In Southern California, we have close to half a dozen sites underway with Southern California Edison, collaborating closely with them to energize these locations either this year or into next. In short, by 2027, you’ll witness a significantly transformed Ionna network in California compared to previously. Among the sites we’re launching in Southern California this year, there’s our first flagship or beacon site in Orange County, conveniently located off the 405. This site isn’t just another set of chargers behind a shopping center; we’re situating 22 high-powered charging bays, alongside a Just Walk Out Amazon-compatible convenience store, outdoor seating, and various amenities in proximity. We are genuinely striving to elevate that charging experience while simultaneously establishing scale.
Joel: Having established that Minnesota serves as a training ground in preparation for LA, the state has unique dynamics where individuals frequently travel to cabins and cottages for weekend road trips, both during summer and winter. As a native Minnesotan, I would be familiar with potential charging stops along I-94 or similar routes heading north. Do you collaborate with local residents when determining charging station locations? How do you approach this?
Seth: We employ what we consider a fairly advanced model to analyze traffic patterns, understanding where people usually travel outside of cities. Typically, during weekdays, individuals move into urban areas, while in Minneapolis, many venture to their cabins. We consistently monitor the outflow of traffic beyond a city, determining both incoming and outgoing routes, while also studying the average daily traffic on roads to gauge potential station sites. For example, St. Cloud is currently undergoing a conversion with Circle K about 90 minutes northwest of the city. Knowing that drivers will head toward Duluth on the weekends allows us to strategically position ourselves along those corridors. We have a comprehensive vacation corridor strategy, whether in Minnesota or Raleigh, where individuals travel toward Wilmington for Wrightsville Beach. We recently launched a site near Wilmington and two additional ones near Myrtle Beach in South Carolina, recognizing the consistent travel patterns towards specific recreational destinations.
Joel: A few days back, during our annual Canadian fishing trip, my dad, some friends and I drove all the way up to Baudette before crossing into Canada. I considered where I would charge if I owned a Rivian R1S or a Lucid Gravity along that route—mind you, that was not a typical trajectory. However, options were limited. On the return journey, it poured the entire time, which made me think about how inconvenient it would have been if I had to exit the vehicle to plug in, especially at a Tesla Supercharger situated in a Target parking lot without protection from the elements—yet every gas station we visited had a canopy. Not all your Rechargeries come equipped with canopies. Can you discuss the decisions regarding the inclusion of canopies versus the absence of them?
Seth: Presently, approximately 30% of our active sites feature canopies. When compared to other networks, whose canopy offerings typically linger in the single digits, we intentionally committed to supplying covered charging options to elevate the user experience. We sought to provide conveniences such as trash cans, squeegees, and protective canopies for drivers utilizing EVs, as these amenities are expected in gas stations. Moreover, it’s infeasible to install canopies everywhere—a challenge exists with regulatory bodies that prohibit canopies within their jurisdictions or due to obstructions caused by nearby signs. We’ve encountered difficulties where planned sites had geological issues, such as a water table rising higher than anticipated, hindering the capacity to erect footers for canopies. In those cases, our priority remains reliable charging over canopies. When feasible, we’ll install canopies; where they aren’t, we focus on delivering dependable, accessible charging.
Kyle: We’ve discussed the partnerships being formed with Circle K, Sheetz, Wawa, Casey’s… Since many of these relate to existing gas stations, I imagine it could become more challenging to establish a new canopy in those locations due to the limited available space when the gas station may already host multiple large canopies. Yet, I feel this could serve as the quickest avenue to augment the number of plugs or bays, rather than solely relying on constructing your own Rechargery stations. Do you perceive these partnerships as the pathway to scaling up?
Seth: It’s undoubtedly a multifaceted strategy. Our partnership with Circle K has proven immensely beneficial. We have assumed control over the majority of their existing US network, retrofitting older 180-kilowatt chargers with our technology. These sites already contain transformers and utility interconnections, expediting certain site transitions, while some of our more complex sites require extended timelines. We’re focused on collaborating with high-caliber, extensive retail partners—Circle K, Wawa, Sheetz, Casey’s—to provide consumers with remarkable amenities, alongside our own locations where necessary, to enhance the overall network.
Kyle: I’d like to understand the structure of these partnerships with the chains. Are you operating under lease terms, paying a monthly fee, or do they receive a portion of the charging revenue? How does this financial arrangement work?
Seth: We operate essentially as tenants in their parking lots. A notable strength of Ionna lies in its foundation and funding from eight established automakers, providing substantial capital and facilitating opportunities for digital integration with these OEMs. If Iona can synchronize digital integration with both OEMs and retail associates, we can concentrate on delivering affordable, reliable, and convenient infrastructure while encouraging collaborative growth between retailers and automakers to enhance driver experiences.
Joel: It’s perpetually puzzled me that no entity—beyond Ionna, Tesla, or Rivian—has partnered with McDonald’s, given their extensive presence across America. It would be an ideal match. Why hasn’t anyone established charging stations in every McDonald’s parking lot?
Seth: Installing charging stations requires adequate space and parking availability. Even at some Circle K or Wawa sites, there are instances where we had to decline locations due to the challenges associated with fitting eight or ten stalls amidst setbacks or regulations dictating how far back from the roadway we need. Each retail establishment is bound by their local zoning regulations demanding minimum parking capacities. Thus, the smaller the footprint of a retailer or quick-service restaurant, the more difficult it becomes to deploy chargers. Many potential locations would be ideal for us, but spatial constraints ultimately dictate capabilities.
Joel: That’s a logical explanation, especially since many McDonald’s do lack expansive parking areas. Interestingly, many of these charging networks pop up in parking lots of Menards, Target, or Walmart due to their ample space. Thank you for clarifying that.
Seth: Absolutely.
Kyle: Concerning the chargers themselves, you utilize Alpitronic hardware; is that correct?
Seth: That is correct.
Kyle: And the software for the systems is managed in-house, right?
Seth: We partner with several providers, meaning we incorporate various software components as needed. We have a charging station vendor, credit card systems… each component requires compatible software. What we’ve developed internally is a comprehensive software platform layer that integrates across all the different values delivered in our network. As we further complicate our sites, our offerings now include electronic locks, surveillance equipment, credit card terminals, and internet service. We’ve developed various software tools for controls, diagnostics, and alerts across our ecosystem.
Kyle: I have a two-part inquiry regarding this: Firstly, what measures have you implemented to overcome reliability issues that have troubled the industry? Many times, half of the chargers at a given station near me are inoperative, which is frustrating. Enhancing uptime would aid everyone in becoming more at ease with public charging. Secondly, I commend your decision to forgo an app. What steps did you take to maintain operations without having a dedicated app for payments and charger locators?
Seth: Regarding reliability, it comes down to the culture we prioritizing as a business. We consistently communicate to our team that the driver is the foremost priority in all decision-making. There are situations where a customer might report that a charger didn’t operate on their first attempt. In response, we have to decide: do we disregard the issue because another user charged without trouble, do we dispatch a technician, or allow some time to see if it eventually functions for someone else? Given our focus on the driver, that drives behavioral variations, leading to a decision of, “Let’s send a technician.” We conduct a health check to validate what the driver has reported. Most of the time the transporter finds it functioning properly, but occasionally we may discover an issue and replace a cable on-site. This commitment permeates our entire organization. When faced with a decision, we always prioritize the driver, shaping our approach. That’s a component of our unique strategy. Alongside that, we’ve instituted various tools for diagnostics and, with the advent of AI, we can infer potential problems more effectively. Our approach involves a “field medic” philosophy: when we suspect a problem exists, we visit the site fully equipped with ten components, bringing a Pelican case filled with parts to potentially fix the charger. We install all ten, then assess what was genuinely the malfunction before proceeding to refine our practices for future visits, thus reducing the number of parts we take next time. It’s an alternative methodology, inspired by our focus on driver experience and prompt resolutions.
Kyle: Before we delve into app functionality, which component tends to fail most frequently on a charger? What’s the most commonly replaced part?
Seth: Physically, it turns out to be the charging cable. It faces misuse, extending from wear and tear, which ultimately impacts performance. We also notice that we need to reboot chargers more often than I would prefer, particularly in regard to credit card readers. Fortunately, our investments in automation have paid off; if we observe a specific behavior, those credit card readers can automatically reboot at night rather than merely increasing manpower to reset them at all times. Having developed software solutions has streamlined this process considerably.
Kyle: There should be a little reset button accessible only through a toothpick, akin to the ones on electronic devices: “Reset,” empowering consumers to handle it.
Seth: Precisely.
Joel: Transitioning to the recent adoption of NACS—the Tesla charging framework as opposed to CCS, which has not aged well—is CCS regarded as more or less reliable than NACS?
Seth: We haven’t identified any performance discrepancies between the two from our customer base. Primarily, our current utilization skews towards CCS; however, we’re witnessing a noticeable increase in demand and faster growth with NACS, attracting more Tesla drivers to our network. Additionally, it’s relevant to note that an increasing number of vehicles sold are equipped with native NACS.
Joel: Just for clarity, several manufacturers have switched to NACS, including Hyundai with their Ioniqs, Rivian for the 2026 model lineup, as well as Subaru and Toyota, with GM also making the switch… And Teslas obviously dominate the market.
Seth: Absolutely.
Kyle: Moving on to automakers, Ionna is distinctive as it’s a venture founded by seven, now eight, automakers. What’s it like managing the expectations of eight different leaders?
Seth: It creates a unique corporate structure and opportunity. The partnership we’ve forged with the eight OEMs is indeed collaborative. Our board comprises individuals from the automakers in an investment capacity, which fosters engagement on oversight and governance. Our outcomes reflect the relationship we’ve nurtured in this venture, especially considering early skepticism surrounding Ionna’s potential success with eight car manufacturers at the helm. It’s not eight automakers building it; it’s a dedicated Ionna team managing operations with guidance from investors focused on particular results: quality at scale within the capital framework. As long as we adhere to that framework, we can effectively conduct day-to-day operations to achieve results. The next aspect involves strategizing how we interconnect with the OEMs and automakers. These manufacturers offer incentives to their clients who charge at Ionna. Furthermore, we’ve extensively focused on Plug & Charge and AutoCharge capabilities collaboratively with all automakers, integrating these features into their applications. Part of our decision not to develop our own app is to prevent hindering automakers and their customers. We strive to provide dependable, affordable, and convenient charging that empowers automakers to sell more vehicles.
Kyle: So it’s not a scenario where GM interjects with, “Hey, we’ve got a significant concentration of GM drivers in this territory, hence you should increase the charger count here,” while Mercedes counters with “No, develop it over there!” It’s not an activist investor vibe?
Seth: No, that wouldn’t yield a successful operation. Such a model wouldn’t withstand; that’s crucial.
Joel: The perceived concern is that Ionna is backed by eight automakers, who are producing and selling vehicles, while also providing the fuel. Should this induce any apprehension in the hearts of consumers, or not really?
Seth: I believe it should be viewed positively—that eight competitive car companies can unify to create and fund such an entity signifying success. Achieving innovation and forward momentum in any sector can sometimes hinge on strategic partnerships. When I saw the announcement in 2023, I thought that this could be a pivotal advancement in ameliorating the charging landscape, and that was my motivation to join forces with the automakers and Ionna, working to realize this shared vision. At times, I reflect on how we’re genuinely pursuing what was laid out in that 2023 press release. It seemed like a monumental undertaking, and the level of involvement and support from the carmakers has been unprecedented.
Kyle: What’s the operational dynamic regarding the automakers’ own charging efforts and partnerships? For instance, GM operates their own branded chargers in collaboration with EVgo at Pilot stores, while Mercedes has been launching their branded charging solutions, yet they are also Ionna stakeholders. How does that coexist while they’re effectively competing as we push to develop a cohesive national infrastructure?
Seth: The need for charging infrastructure across the country is extensive, as you are all aware. Presently, there are EVs already on the roads lacking the necessary charging options, and this trend continues with new models being rolled out yearly, leaving us with a shortfall. Certain legacy programs established prior to our venture remain active. These entities function independently and there’s no interaction between them and Ionna. This landscape allows for broader penetration into the EV charging domain. However, Ionna proves unique as a strategic coalition involving eight automakers working collectively toward a common goal.
Joel: What’s the pacing here? How rapid must our chargers be and how promptly should they deliver charges? News just surfaced from China concerning their “five-minute charging” that allegedly reaches 70%, claiming the rest of the world is lagging behind. Yet, we already have rapid advances. I drove a Volvo EX90 in June, charging at a 350-kilowatt station at an EA stop at Menards in Alexandria, and found that it only took 18 minutes to charge from 44% to over 90% as it peaked at around 315 kilowatts. How fast must we become, or is this merely showcasing China’s capabilities?
Seth: Nobody fills their gasoline vehicle by rushing—jumping out to refuel as quickly as they can and retreating into their vehicle. Several contemporary gas stations resemble cafes more than service stations. Consider Wawa, Sheetz, Casey’s, Buc-ee’s, and Wally’s—these establishments enjoy providing a space where customers spend time inside the store. Many find that their profits stem primarily from spending within the shop while fueling becomes secondary to that experience. The notion that charging must be achieved in five minutes or else people won’t invest in EVs is flawed. Evidence of this is reflected in the fact that, in July, 6% of all vehicles sold were still electric, thanks to the existing infrastructure and vehicle technologies. The target should be aiming for a charging duration of 10 to 20 minutes; that timeframe accommodates activities like restroom visits, grabbing a meal, stretching legs, or walking a dog instead of racing to refuel and rush back in. I don’t believe that’s the real experience people envision.
Joel: As a father to two kids, a couple of Christmases ago we drove to Iowa during a snowstorm. I counted the time from parking to resuming our drive: from parking, everyone headed into the restroom, grabbed a meal, and filled up the car with gas. It clocked in at 31 minutes. With four of us, it only took a minute. If I were driving a Rivian, Lucid, or an Ioniq 9, that would have sufficed during a Supercharger’s wait. That’s the reality of it.
Seth: Absolutely, you got it. Everything we now deploy operates at 400 kilowatts; our next generation sites are targeting 500 kilowatts. Beyond that threshold, I don’t see the necessity. I genuinely don’t.
Kyle: I resonate with your principles, yet I’m curious about your perception: many EV owners believe that a DC fast charger should function as their primary charging source, while many automakers recommend routine charging at home each night, suggesting DC fast chargers are mainly for road trips. While a 30-minute stop might be warranted during a family trip, that isn’t ideal for weekly commutes> Would you prefer focusing on those types of drivers, or is the primary use case for DC fast charging not this?
Seth: 70% of our investments are earmarked for urban development. We’re constructing in Orlando, Tampa, and Jacksonville. Our interstate expansion in Florida is minimal. It’s not particularly easy to facilitate home chargers; there are older properties, and the costs can be prohibitive. Thus, we must prioritize ensuring that densely populated urban areas have charging provisions for those who can’t charge at home or need additional options.
Kyle: The actual dream is for everyone to have DC fast chargers at home.
Seth: At home, I assume utilities would have a mixed perspective on that.
Kyle: I contacted Southern California Edison; they are not supportive, unfortunately.
Joel: Tesla has done an admirable job setting benchmarks, but no one seems to excel in grocery store installations. I’m unclear why we haven’t established charging stations in grocery stores back here in Minnesota…
Seth: Have you visited our Hy-Vee location? We’ve positioned a couple of them in Minnesota. I’ll send you a list following this conversation.
Joel: I’ve installed a home charger. We’ve got one at the cabin, and one here. However, rapid charging while visiting family or on road trips is vital. Most Americans live in non-single-family homes—an immense market.
Kyle: And I’m among the EV owners without home charging access, which explains my inquiries.
Seth: It can indeed be challenging.
Kyle: Thus, it genuinely is a challenge. Living in an outdated house, lacking a garage, renders installations costly, and I’m on a two-year lease.
Seth: Our initial home was in a 1930s-built Connecticut property. I used Level 1 charging consistently, as it was impossible to establish a Level 2 charger from my basement to the detached garage located in the rear of the yard, so I relied on an extension cord every evening.
Joel: I hope that was safe!
Seth: Rest assured, it was properly rated and sufficiently installed.
Kyle: Thank you so much for your time, Seth Cutler. I genuinely appreciate it.
Seth: Thank you for having me. I truly appreciated the conversation.
Joel: We’ll definitely welcome you back, thank you.
Seth: Absolutely, thanks everyone.